
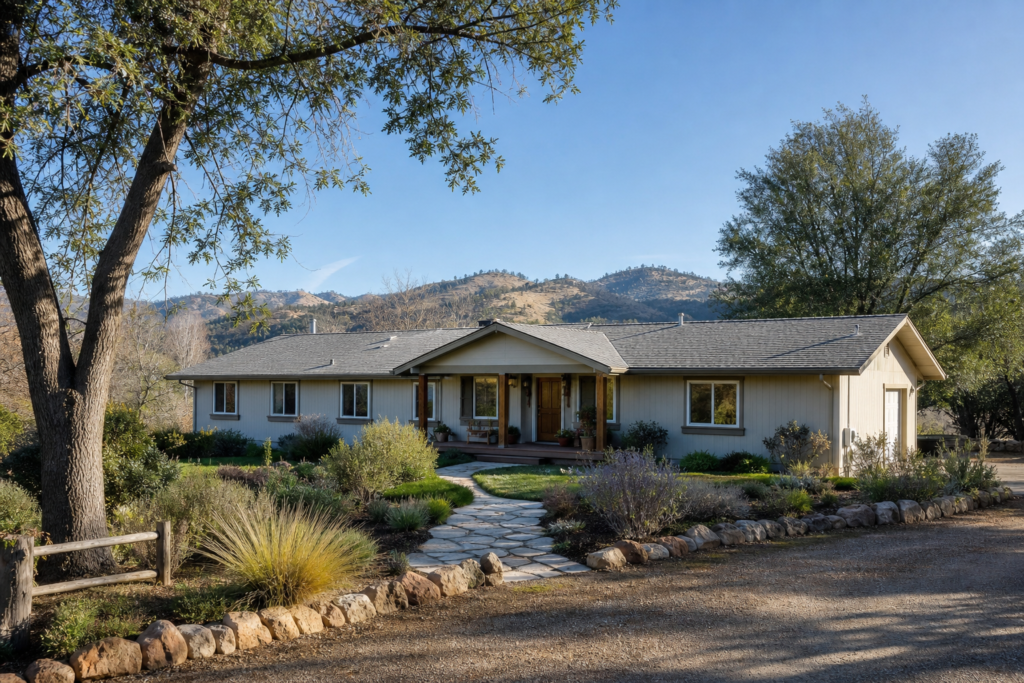
A property in Esparto or Capay Valley can qualify for an FHA loan if it meets HUD’s safety, soundness, and security standards. Rural location alone is not a disqualifier, but private wells, septic systems, manufactured homes, and acreage all require additional lender review before you rely on FHA financing.
Does a Capay Valley property qualify for an FHA loan?
A rural property in Esparto or Capay Valley can qualify for FHA financing, but the property itself has to pass HUD’s standards for safety, soundness, and security, not just the borrower’s credit and income. Private wells, septic systems, older homes, manufactured housing, and acreage all introduce variables that a conventional suburban transaction simply doesn’t have. Getting those details sorted before you make an offer is what separates a smooth closing from a deal that falls apart in escrow.
Key Takeaways
- Rural location alone does not disqualify a Capay Valley property from FHA financing, the property must meet HUD’s property standards for safety, soundness, and security.
- Recent local market data shows the Esparto area median sale price at $435,000, with homes averaging 48 days on market, well within FHA loan-limit territory for most buyers.
- The 2026 national FHA floor for a one-unit property is $541,287; the applicable Yolo County limit must be confirmed through HUD’s county-level lookup before you structure your offer.
- Private wells and septic systems are financeable under FHA, but lenders will require documentation, inspections, and possibly water-quality testing, get that checklist from your lender before relying on the seller’s existing records.
- An FHA appraisal is not a substitute for a buyer’s inspection; arrange your own well, septic, roof, foundation, and electrical inspections separately on any older rural property.
What does FHA actually look at when a Capay Valley property qualifies?
The FHA loan program insures the lender against default, which means HUD requires the property to meet its Minimum Property Standards before it will back the loan. The appraiser evaluates the home’s condition through the lens of safety, soundness, and security. That’s the framework that matters.
For a typical Esparto or Capay Valley property, the appraisal will focus on:
- Roof condition and remaining useful life
- Foundation integrity
- Electrical service and panel adequacy
- Plumbing functionality
- Heating systems
- Access to the property (legal, year-round)
- Water source and wastewater disposal
- Any visible health or safety hazard
If the appraiser flags a deficiency, the lender will typically require it to be corrected before the loan closes. That can mean seller repairs, a repair escrow where the lender permits one, renegotiation of the purchase price, or, in some cases, switching to a different loan program entirely. The exact remedy depends on the defect, the lender’s own policies, and how the purchase contract is written.
This is exactly the kind of scenario I walk my clients through before we even make an offer. Knowing the property’s condition early gives you leverage. Discovering it after the appraisal puts the timeline at risk.
Where do Esparto-area prices land relative to FHA limits?
Recent local market data shows the Esparto area median sale price at $435,000, with homes averaging 48 days on market. That median sits below the 2026 national FHA floor of $541,287 for a one-unit property, according to HUD’s single-family lending guidance. For most buyers targeting Esparto, the loan limit itself is unlikely to be the binding constraint.
Winters and Woodland carry higher medians, as the table below shows. If you’re considering properties across multiple areas, the loan limit conversation may look different depending on where you land.
| Area | Median Sale Price | Median Days on Market |
|---|---|---|
| Esparto | $435,000 | 48 |
| Woodland | $555,000 | 46 |
| Winters | $683,500 | 56 |
These are area-level medians from recent local market data (trailing roughly 90 days, as of September 2026). An individual home’s value depends on condition, street, build year, and timing. The applicable Yolo County FHA limit must be confirmed through HUD’s official county-level lookup, the national floor and ceiling are not automatically the local limit. And remember: the loan limit caps the mortgage amount, not the purchase price. Your down payment, appraisal, and underwriting all factor into what you can actually buy.
The rural property issues that trip up FHA buyers in Yolo County
Most of the FHA complications I see in Esparto and Capay Valley don’t come from the borrower’s file. They come from the property itself. Here’s where buyers run into trouble, and where understanding whether your Capay Valley property qualifies for FHA comes down to specifics, not just location.
Private wells and septic systems
A property served by a private well and septic system can be FHA-financeable, but it adds a layer of due diligence that a city-water home doesn’t require. HUD guidance identifies permanent utility connections, including an acceptable well-and-septic arrangement, as part of property eligibility. Your lender will want to know the well’s condition, water quality, distance from the septic system, and whether the system is functioning properly.
Requirements vary among FHA-approved lenders. One lender may require a full water-quality test; another may have a different checklist. Get your lender’s specific requirements in writing before you rely on whatever documentation the seller already has on file. Seller records are a starting point, not a guarantee.
Acreage and outbuildings
Acreage alone does not disqualify a property from FHA financing. The key question the appraiser and lender are asking is whether the property is primarily residential and whether the site, improvements, access, and utilities support the mortgage. A property with a few acres and a barn is very different from a working agricultural operation, but both can raise questions that need answers before you’re in contract.
Outbuildings, barns, workshops, detached garages, solar equipment, pools, can affect the appraisal and underwriting even when they’re not the main house. Be upfront with your lender about what’s on the property and how you intend to use it. If a structure raises a zoning, safety, or valuation flag, it’s better to know before the appraisal than after.
If you’re considering a property that crosses into genuine agricultural territory, the financing conversation shifts. I’ve written about the distinction between residential rural properties and working agricultural assets in my post on tips for first-time homebuyers, and it’s a conversation worth having early.
Manufactured homes
Manufactured homes are common in parts of rural Yolo County, and FHA does have a path to financing them, but the requirements are specific. According to HUD’s manufactured housing guidelines, an FHA-eligible manufactured home generally must:
- Have at least 400 square feet of living space
- Have been built after June 15, 1976
- Comply with federal manufactured-home construction standards
- Remain on a permanent chassis
- Be placed on a permanent foundation meeting FHA requirements
- Have the mortgage cover both the home and its site
Before you make an offer on a manufactured home, verify that the HUD certification label is present and that foundation documentation exists. Missing or incomplete documentation can stop a transaction cold. This is one area where doing the homework before the offer, not after, protects every dollar of equity you’re putting in.
Older homes and condition issues
Esparto and the Capay Valley have a lot of older housing stock. An older home isn’t automatically ineligible for FHA financing, but it is more likely to have the kinds of deferred maintenance, outdated systems, or visible defects that an FHA appraiser will flag. Roof, foundation, electrical, and plumbing are the most common.
One thing I always tell buyers: the FHA appraisal is done for the lender and the insurance decision, it is not a comprehensive inspection of the property. Arrange your own inspections for well, septic, roof, foundation, and electrical systems, especially on an older rural home. The appraisal may miss things that a dedicated inspector would catch, and you need that information to protect yourself regardless of how the financing is structured.
If repairs are required before the loan can close, your options depend on the defect, the lender’s policies, and what’s negotiated in the purchase contract. Some lenders allow a repair escrow or holdback; others require the work to be completed before closing. Know your lender’s position on this before you’re in contract, not after the appraisal comes back with a list.
For a broader look at how the local market has been moving across Yolo County, the Yolo County Real Estate Market Update provides useful context on pricing and inventory trends across the region.
If you’re a first-time buyer working through this process, the First-Time Buyer to Move-Up Seller in Esparto post walks through how the buying decision evolves as you build equity in this market.
If you’re asking whether a specific Esparto or Capay Valley property qualifies under FHA requirements, the honest answer is: it depends on the property. Your specific situation, the home’s age, utilities, foundation, outbuildings, acreage, and your lender’s overlays, is what determines whether FHA is the right path or whether a different loan structure makes more sense. That’s a conversation worth having before you’re in contract, not after.
To read what other buyers and sellers say about working with me, check my reviews on Google, Zillow, and Realtor.com.
FAQ
Can I use an FHA loan to buy a home with a private well in Esparto?
Yes, a private well does not automatically disqualify a property, but your lender will require documentation, inspection, and likely water-quality testing before the loan can close. HUD guidance requires an acceptable water source as part of property eligibility, and requirements vary among lenders, so get your lender’s specific checklist in writing before you rely on the seller’s existing well records.
Can I buy a manufactured home in Esparto with FHA financing?
FHA financing is available for manufactured homes that meet HUD’s specific requirements, including being built after June 15, 1976, having at least 400 square feet, sitting on a permanent foundation, and having the mortgage cover both the home and the land. Before you make an offer, verify that the HUD certification label is present and that foundation documentation is available, missing paperwork is one of the most common reasons manufactured-home FHA transactions stall.
Does an older rural home in Yolo County have to be repaired before an FHA loan can close?
Only if the appraiser identifies defects that affect the property’s safety, soundness, or security. Not every older home requires repairs, but roof, foundation, electrical, and plumbing issues are the most common flags on older rural properties. If repairs are required, the resolution, whether seller repairs, a repair escrow, or renegotiation, depends on the defect, the lender’s policies, and what’s written into your purchase contract.
Is the FHA loan limit high enough for homes in Esparto or the Capay Valley?
For most buyers targeting Esparto, where the area median sale price is around $435,000, the FHA loan limit is unlikely to be the binding constraint. The 2026 national FHA floor for a one-unit property is $541,287, but the applicable Yolo County limit must be confirmed through HUD’s county-level lookup, and the limit caps the mortgage amount, not the purchase price, so your down payment and underwriting also factor in.
Can I use FHA financing for a property with acreage in rural Yolo County?
Acreage alone does not disqualify a property from FHA financing. The appraiser and lender will evaluate whether the property is primarily residential and whether the site, utilities, access, and improvements support the mortgage. Properties with barns, outbuildings, or agricultural features may require additional lender analysis, so disclose what’s on the property and ask your lender to review the specific address before you make an offer.
Does an FHA loan require me to live in the Esparto property?
Yes, FHA loans are owner-occupancy programs. You must intend to occupy the property as your primary residence; FHA financing is not available for investment properties or second homes. If you’re considering a property as a rental or part-time residence, you’ll need to discuss alternative financing options with your lender.
Before you make a move on a property in Esparto or Capay Valley, get the property-level details sorted. The difference between a smooth FHA closing and a derailed transaction often comes down to what you knew, and when you knew it. Call or text me at 530-713-6121, or email me at l.pillard@gmail.com, and I’ll walk you through what to look for on any specific property before you’re committed to a contract.
To learn more about my experience, local knowledge, and approach to protecting my clients, visit LindaPillardRealEstate.com and explore my Real Estate Library, including books and original resources created to help buyers, sellers, and property owners make confident, informed decisions.
Equal Housing Opportunity. Linda Pillard, CalDRE #01208519, Green Fields Real Estate Services – Linda Pillard Real Estate, licensed by the California Department of Real Estate (CalDRE). This article is general information only and is not legal, tax, or financial advice. Confirm your specific loan terms, property eligibility, and costs with your lender, closing agent, and tax advisor.